
OCTOBER 2026
ISSUE 08
AIG QUARTERLY
Welcome to the eighth edition of Art Intelligence Global’s quarterly newsletter. Informed by our extensive global reach, our reporting covers major developments and in-depth analysis of the international art market. If you would like to discuss further, please contact us at info@artintelligenceglobal.com.

October: Frieze London & Art Basel Paris
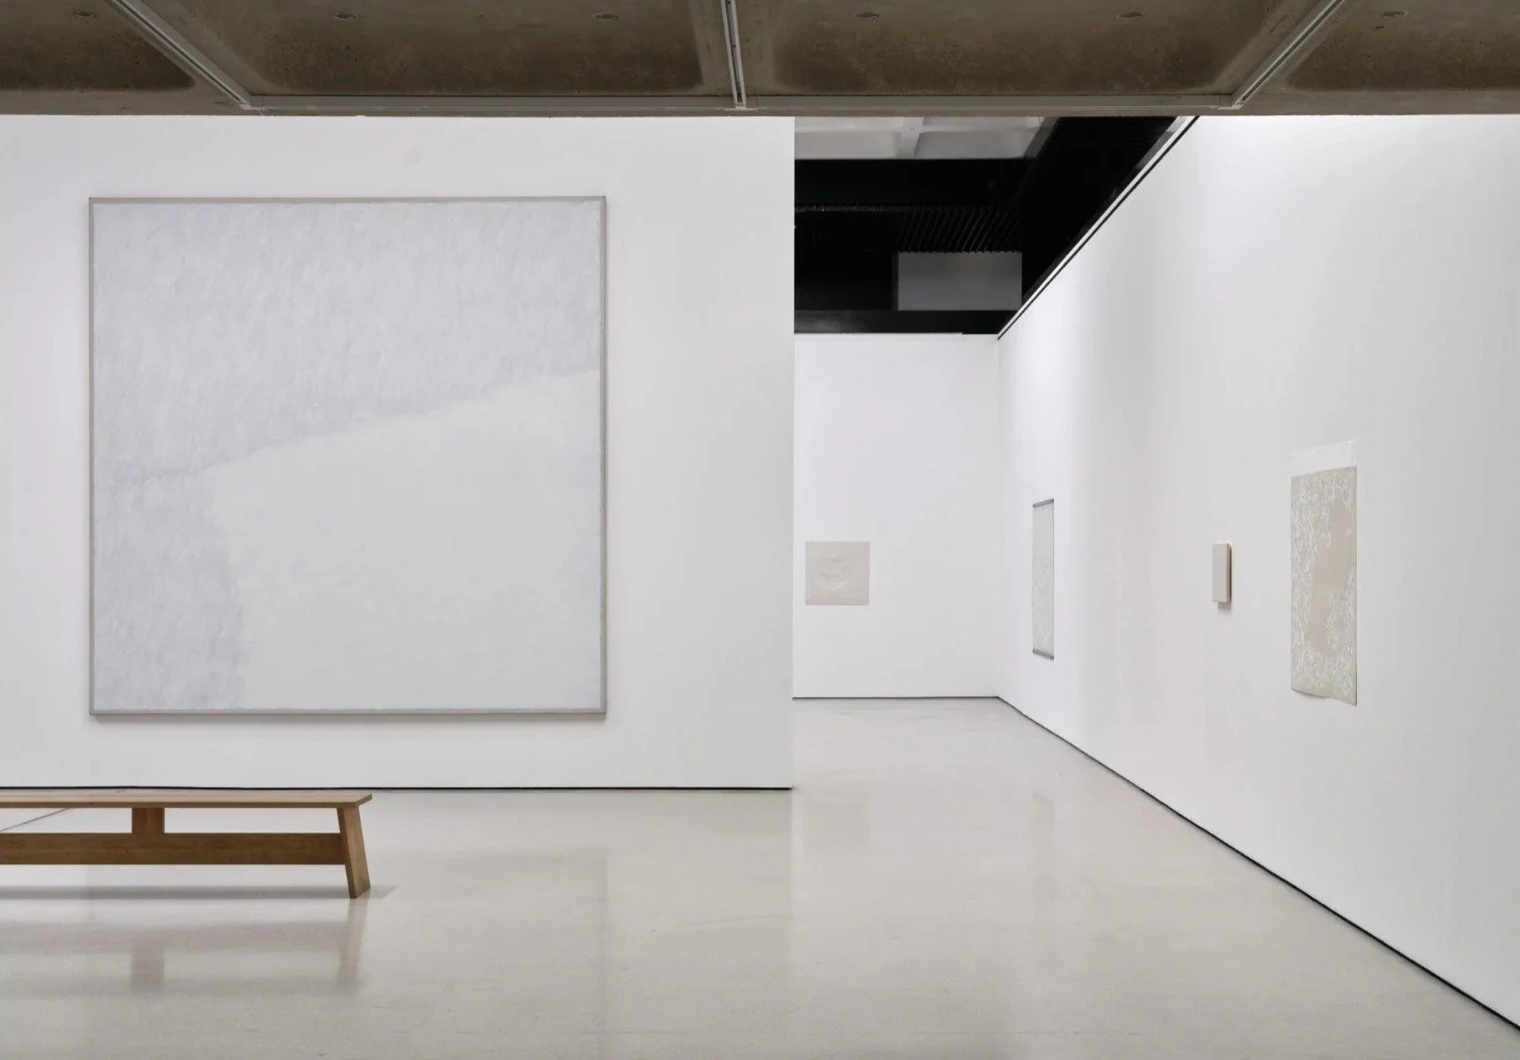
October has become synonymous with the international art world’s descent on Europe, and this year’s calendar provided the first major tests of market sentiment after the summer hiatus. In London, expectations for Frieze had been tempered somewhat from the highs of the previous decade, shaped by Brexit, a softer economic and wealth-creation outlook in the UK, and the rise of Art Basel Paris across the Channel the following week. Perhaps because the bar had been set lower, the mood among dealers and collectors proved more upbeat than anticipated: contemporary sales were happening at a frequency closer to pre-Covid levels, and an influx of younger UK-based galleries created fresh opportunities for discovery. At Frieze Masters, even as a growing number of established global galleries are opting out, the fair’s confluence of antiquities, Old Masters, and modern material offered surprising juxtapositions and historical discoveries found nowhere else during the October season. After a few years in which attention has gravitated towards across the Channel, the value and relative stability of London’s art world ecosystem is forging a happy co-existence with Paris. This is undoubtedly aided by the continued strength of the city’s institutional shows, with Robert Ryman at the Barbican and the Royal Academy’s exploration of turn-of the-century artists’ relationship with the French Riviera drawing particular acclaim.
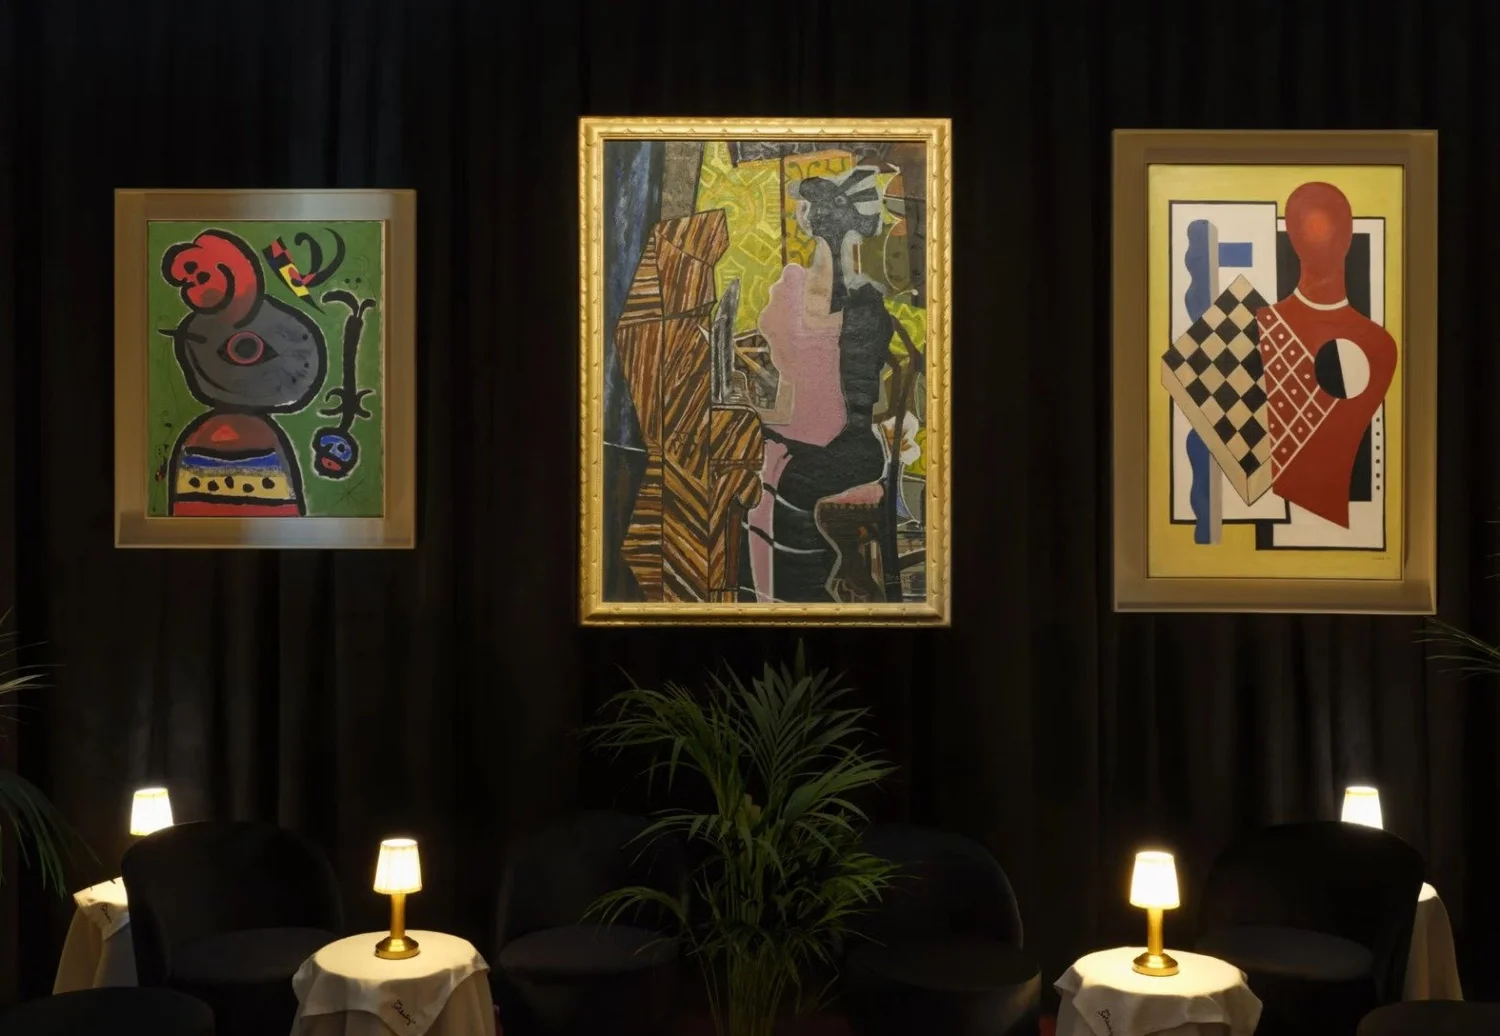
In Paris, the number of deep-pocketed American collectors on the ground, together with the caliber of the work assembled to greet them, continues to overshadow London. Violent protests across France raised security concerns that prompted some collectors to cancel their flights and ultimately led to the fair being curtailed ahead of the weekend. Still, the enduring appeal of the city, its programming, and the premium Art Basel brand as a magnet for American buyers should not be underestimated: this remains the deepest client base in the market, and it continues to fuel trade globally. The importance of face time with these collectors, and of having something new to show them, was most clearly evident in the pop-ups staged outside the main fair, among them Pace Di Donna Schrader’s salon-style installation in a classic Haussmannian apartment and a temporary restaurant, Chez Sotheby’s. There were, however, possible signs of strain. The work brought to the fair was less high-profile, and less expensive, than in recent years, perhaps a consequence of galleries’ constant pressure to source fresh material for a relentless cycle of fair presentations. A sense of saturation was also palpable: with two weeks of auctions to contend with as well, collectors and dealers alike are being confronted with a vast volume of material, making conviction harder to come by, particularly when similar works may surface in the near future. Excitement for the fair felt more measured than in its earlier editions, suggesting that Art Basel Paris has settled into its role as an established fixture rather than a novelty.
Kicking off the fortnight of auctions that accompany the two fairs, Christie’s headlined the October auction season with the sale of British fashion mogul Peter Simon’s collection. Following the now well-established practice of building dynamic marketing assets to drive collector engagement and tell a story around a group of works, Christie’s ran a campaign exploring the relationship between Simon’s career in fashion (the sale was titled Monsoon, after his high-street brand) and the aesthetics that shaped his collection. Developed with input from the pioneering dealer Ivor Braka, who was, himself, unusually, the subject of content produced by the auction house, the sale was particularly strong in modern and contemporary British art. Hurvin Anderson, Bridget Riley, Leon Kossoff, David Bomberg, Peter Doig and Francis Bacon all achieved strong prices, while rare works by European masters, including Fernand Léger, Liubov Popova, and Joan Miró, also performed well. Including day sales, the collection realized a total of £118.5M, becoming the most valuable single-owner series Christie’s has sold in London. Although it lacked the depth of modern masterpieces that were a hallmark of Sotheby’s major Lewis Collection sale in the city earlier this year, strong bidding for British artists proved that matching local collecting tastes to the right property continues to have an outsized effect on results. (Notably, both houses have now moved their Modern British sales to the week after Frieze rather than later in November, seeking to capture international visitors’ attention and capitalize on the fair’s momentum.)
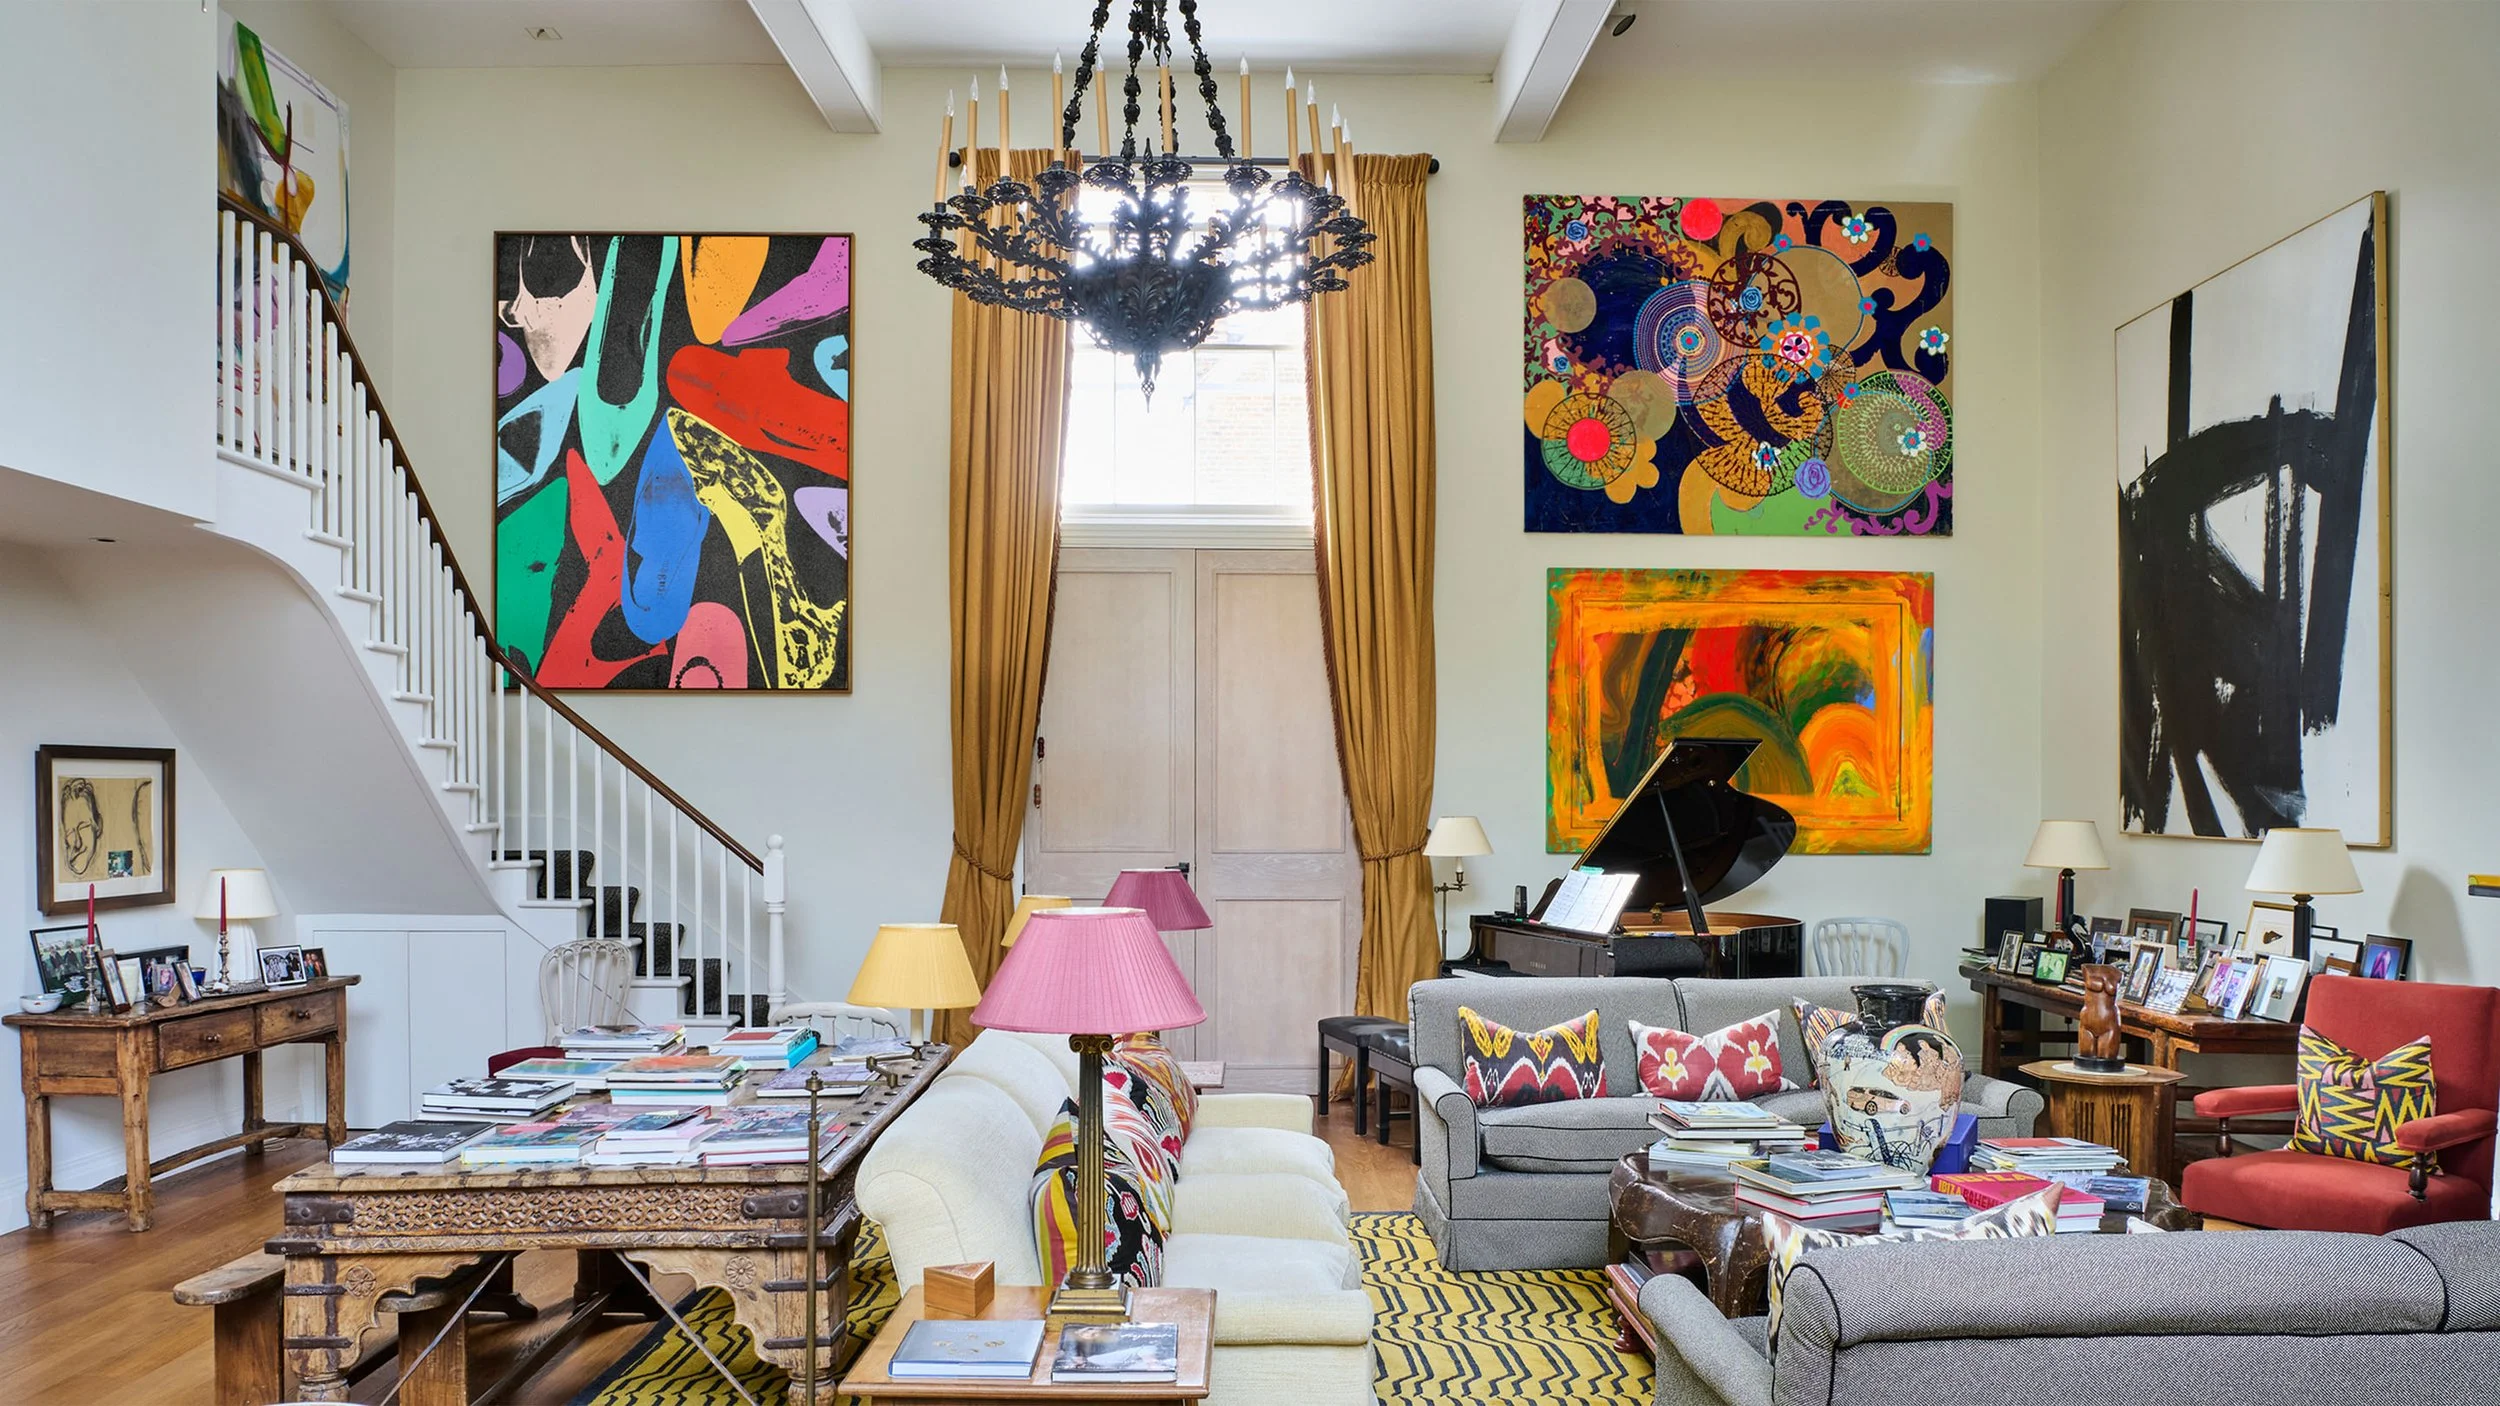
The all-round success of the Simon Collection reinforced a narrative that has prevailed for the last few years: a major single-owner collection anchors an auction season, supplying both a wealth of fresh-to-market works and the chance to build a coherent, multi-platform story that lifts attention for lots across the price spectrum. Christie’s continued to achieve a number of strong results in the subsequent £111.1M 20/21 Century Evening Sale – including a £31.6M Kandinsky and a £25.2M Mondrian – although the energy of the Simon collection was not matched to the same degree. At Sotheby’s, by contrast, the lack of a comparable anchor was felt in the house’s various-owner evening sale. Amid subdued and cautious bidding, few lots captured bidders’ attention, producing a sell-through rate of 73% and a total of £45.9M. Whereas Christie’s was buoyed by numerous high-quality examples by British artists, at Sotheby’s the muted results for artists with more international markets (such as Andy Warhol, Willem de Kooning, Mark Rothko, Gerhard Richter, and Yayoi Kusama) pointed both to full estimates and to the limited upside, for many market stalwarts, of selling in London rather than New York.
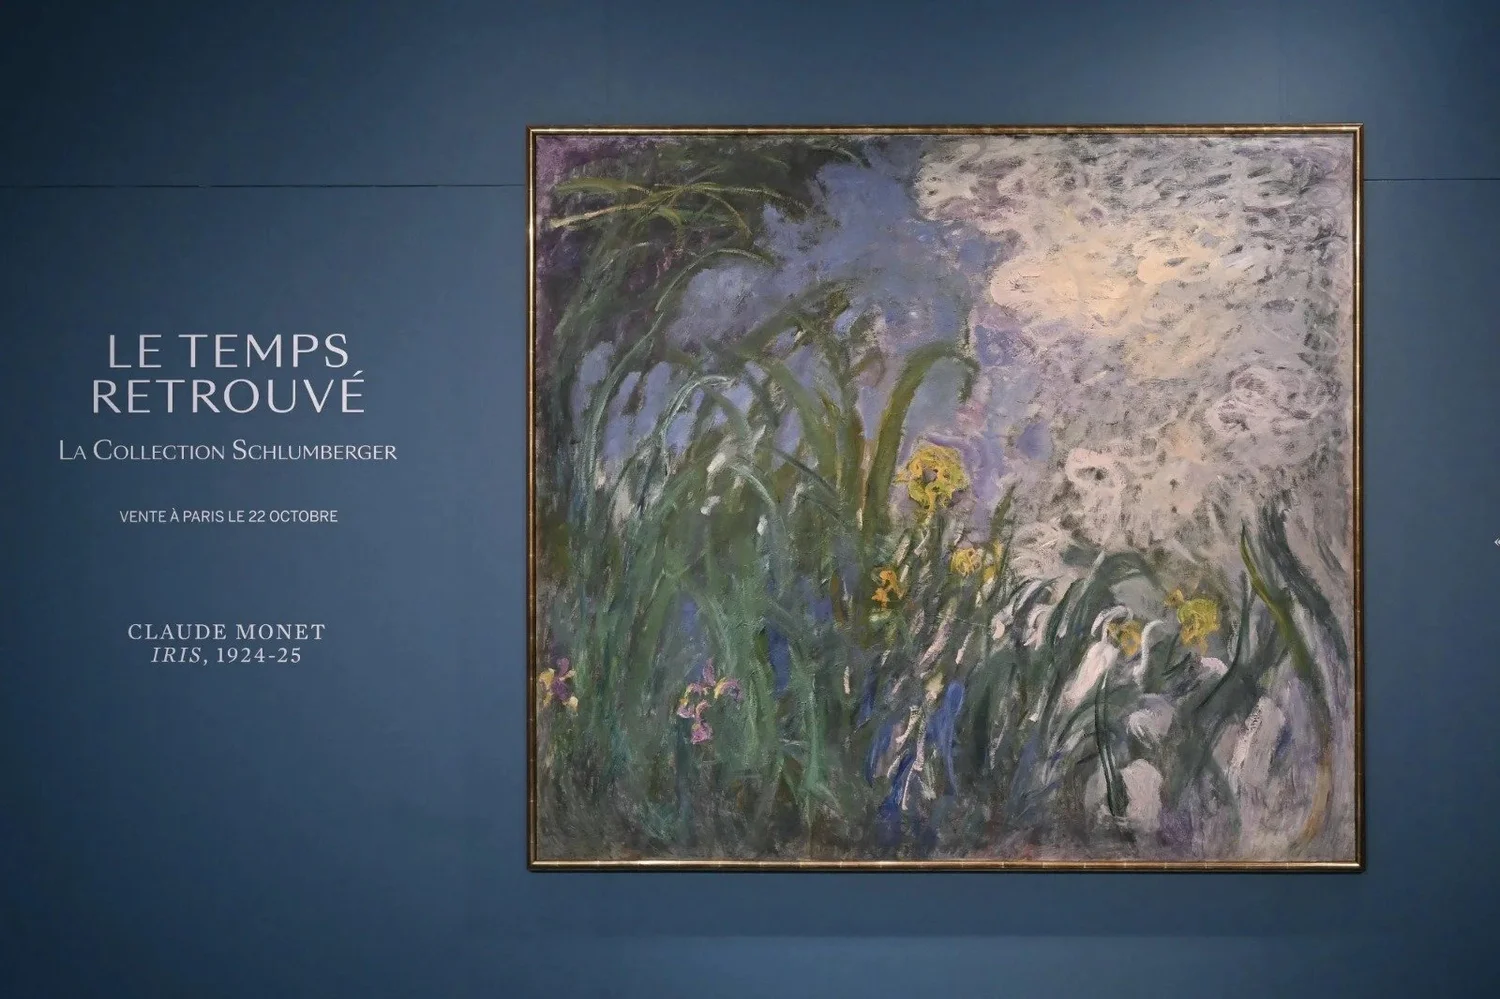
In Paris, the auction houses have adjusted and expanded their offerings since Art Basel Paris launched in October 2022. Many collectors now regard it as the world’s premier fair, and it continued to draw large numbers of international visitors this year, even amid the threat of protests in the air. Each house secured a prestigious collection to headline the week, both featuring prominent works by Claude Monet, arguably the most celebrated of the Impressionists. At Sotheby’s, the late canvas Iris (c.1924–25), held in the Schlumberger Collection for nearly a century, more than doubled its low estimate in selling to a Chinese buyer for €50M (becoming the most expensive work ever auctioned in France), lifting the consignment to a total of €74.4M. At Christie’s, property from the family of the famed dealer Paul Durand-Ruel included a €12.8M Monet landscape, alongside canvases by Pierre-Auguste Renoir, Camille Pissarro, Alfred Sisley, Pablo Picasso, and Gustave Loiseau, among others.
Staged alongside relatively strong various-owner evening and day sales, these collections helped the houses to bring in nearly identical totals of €137,646,552 (Sotheby’s) and €137,585,856 (Christie’s), the strongest October sales series to date. Indeed, this season has cemented the growth of Paris’s October leg since Art Basel’s arrival: between 2017–21, the houses sold a combined €388.3M worth of property in October, a figure that has since risen to €848.9M between 2022–26, a gain of 119%. Marquee Paris Modern and Contemporary auctions previously took place in December, so the move to October, along with the increase in high-caliber material on offer, signals a response to the influx of deep-pocketed international collectors and the momentum generated by the world’s most prestigious fair brand. Notably, Phillips also conducted their first ever sale in the city during the fair, realizing a respectable €4.87M across 53 lots. The Paris sales have undoubtedly benefited from their proximity to the fair, with major collectors arriving to the city with the intent to spend and often finding offerings at auction more enticing or better value than comparable works offered at Art Basel itself.
That said, the enthusiasm of the Paris sales could not hide some disappointing moments and high-profile misses. Sotheby’s Modernités sale had a sell-through rate of only 73%, with works by Jean-Michel Basquiat, René Magritte, Donald Judd, Georges Seurat, and Monet going unsold, while Christie’s withdrew a 1957 Joan Mitchell canvas estimated at €5–7M. Whether or not these results were a consequence of buyer fatigue, the market remains selective and, with the supply of material for certain artists showing no sign of abating, very price-sensitive. Looking ahead to the marquee sales in New York next month, the signs are that collector activity remains reassuringly high. A premium is placed on scarce, high-caliber works by blue-chip artists; this bodes well for the houses, which have each assumed significant guarantee risk to win the Blaquier-Arrieta (c.$450M), Baum (c.$100M), Koons (c.$100M), Sonnabend (c.$60M), and Lust (c.$60M) collections. As has been the case for a number of seasons, mid- and lower-tier works may give the most cause for concern and will need to be sensitively priced to attract bidders and cut through the growing sense of collector saturation that only the most exceptional lots can consistently defy.
Lot Picks
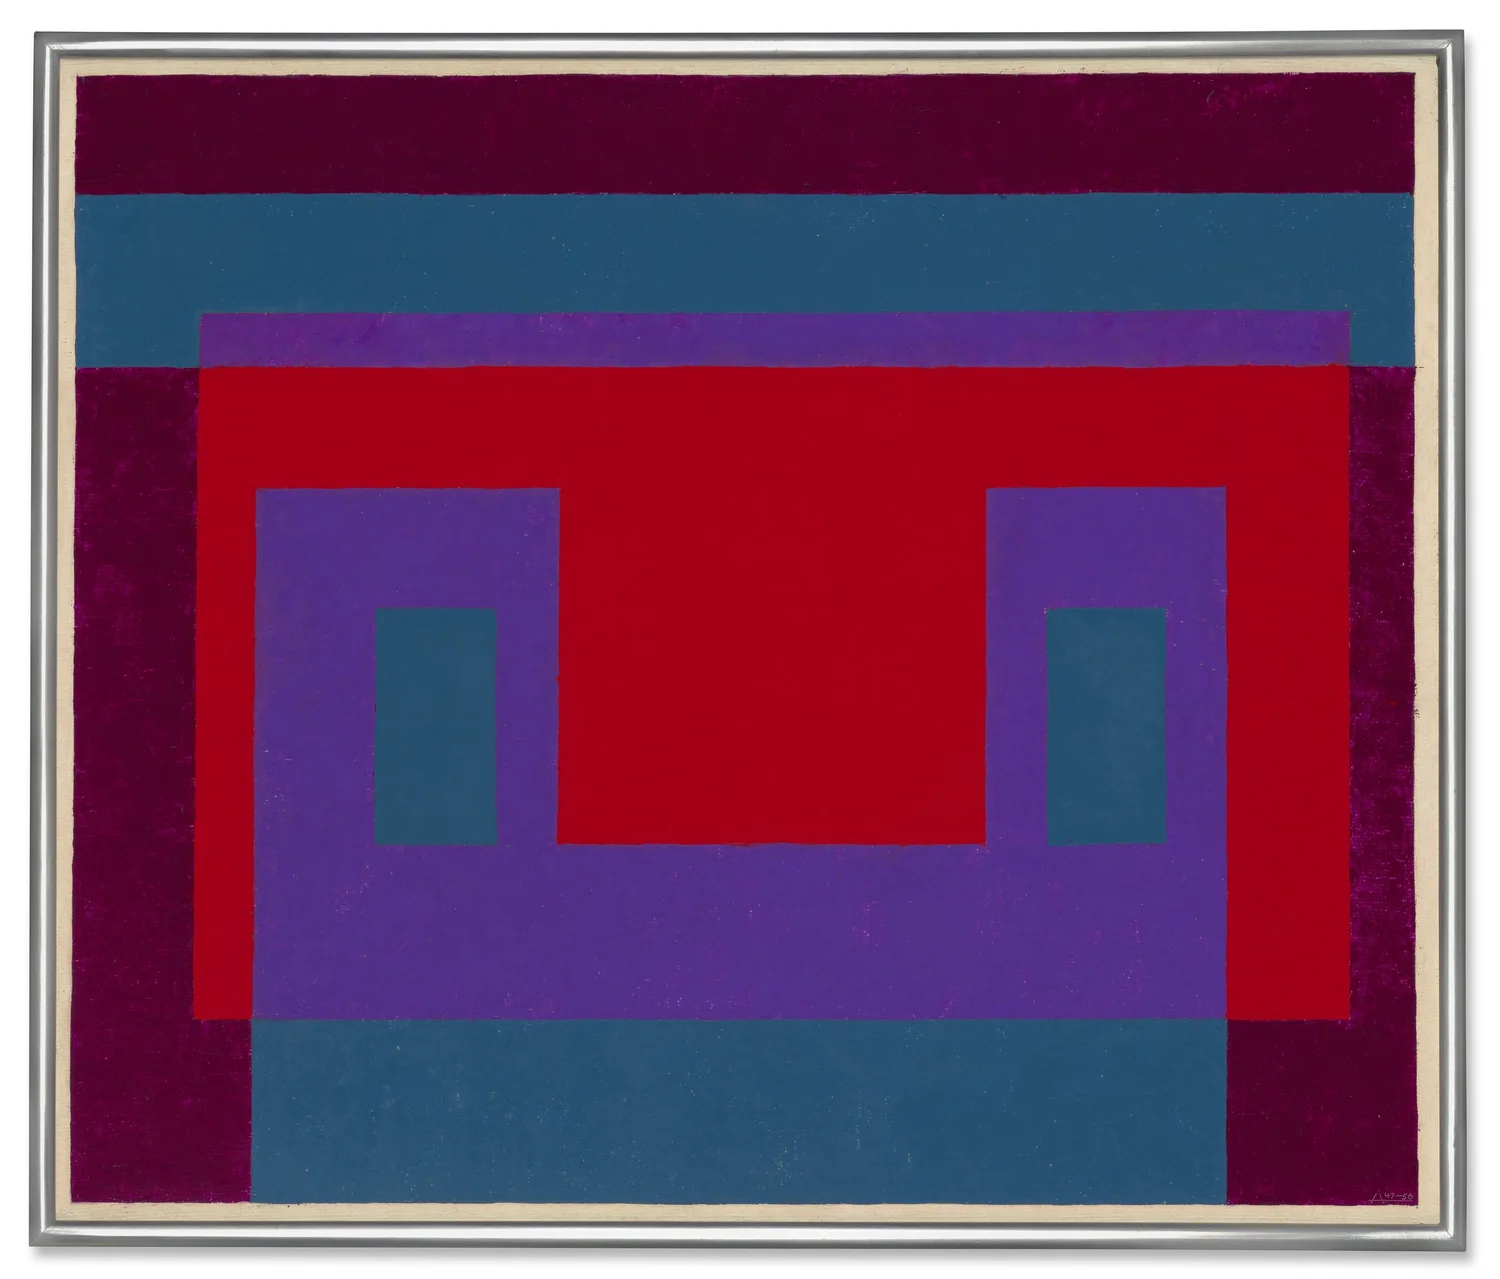
JOSEF ALBERS
Red Front (1947–56)
oil on Masonite
55.9 x 66 cm. (22 x 26 in.)
Christie’s London, Post-War & Contemporary Art Day Sale, Lot 327
Estimate: £220,000–350,000
Sold: £704,000 ($933,191)
The market for Josef Albers’ work continues to strengthen: at Christie’s, Red Front set a new auction record for an example of the Variant series. Informed by the adobe houses that populated Mexico and New Mexico, the color block structure of the series cemented his investigation of geometry and color, later informing his renowned Homage to the Square compositions.
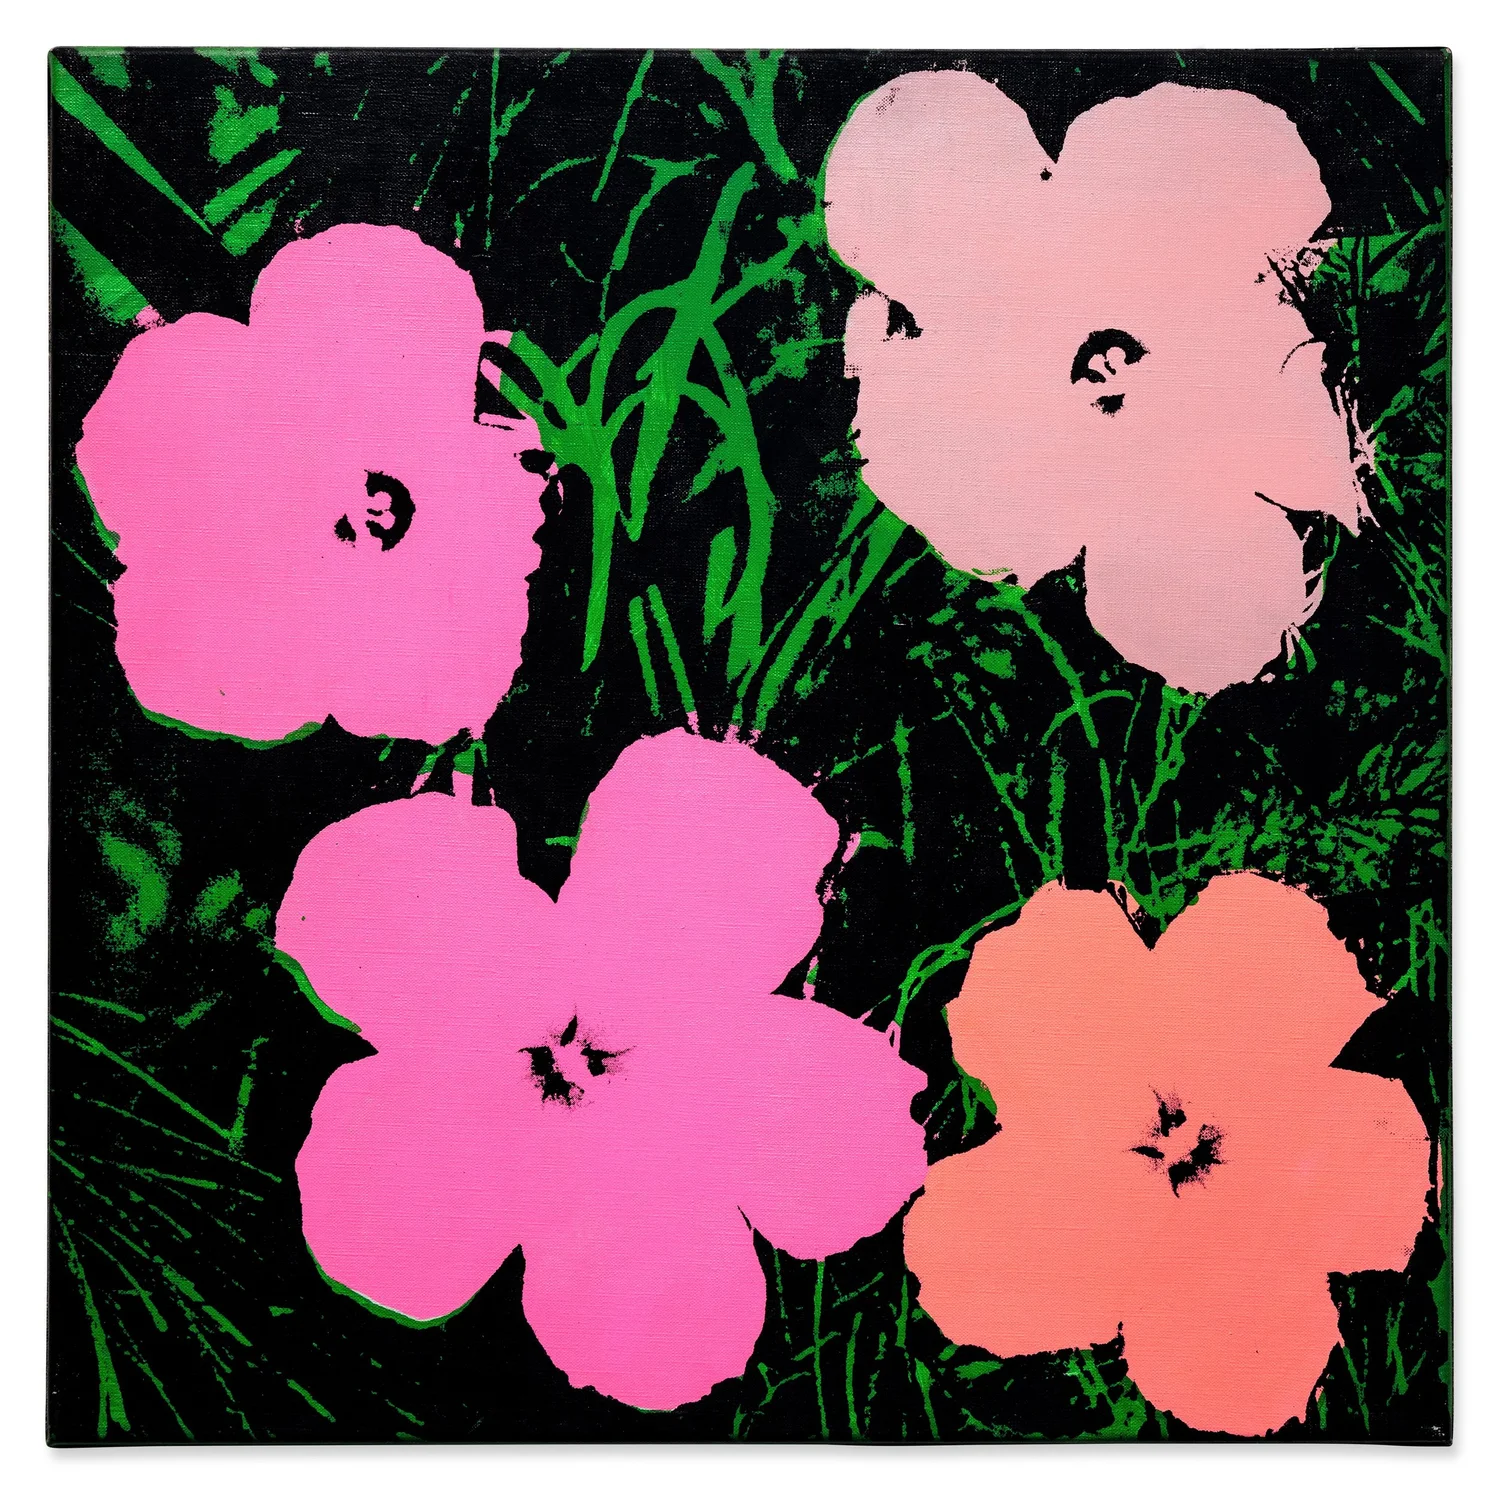
ANDY WARHOL
Flowers (1964)
acrylic and silkscreen on canvas
61 x 61 cm. (24 x 24 in.)
Sotheby’s, Contemporary Curated, 8 October 2026, Lot 121
Estimate: $2,500,000–3,500,000
Sold: $6,342,000
This vibrant Warhol Flowers, held for 60 years in the collection of the renowned architect Robert A.M. Stern, sold at Sotheby’s mid-season sale earlier this month. Featuring a desirable palette, the present work set a new auction record for a Flowers painting, capping off a period of renewed momentum and demand for the series.
Museums and Markets
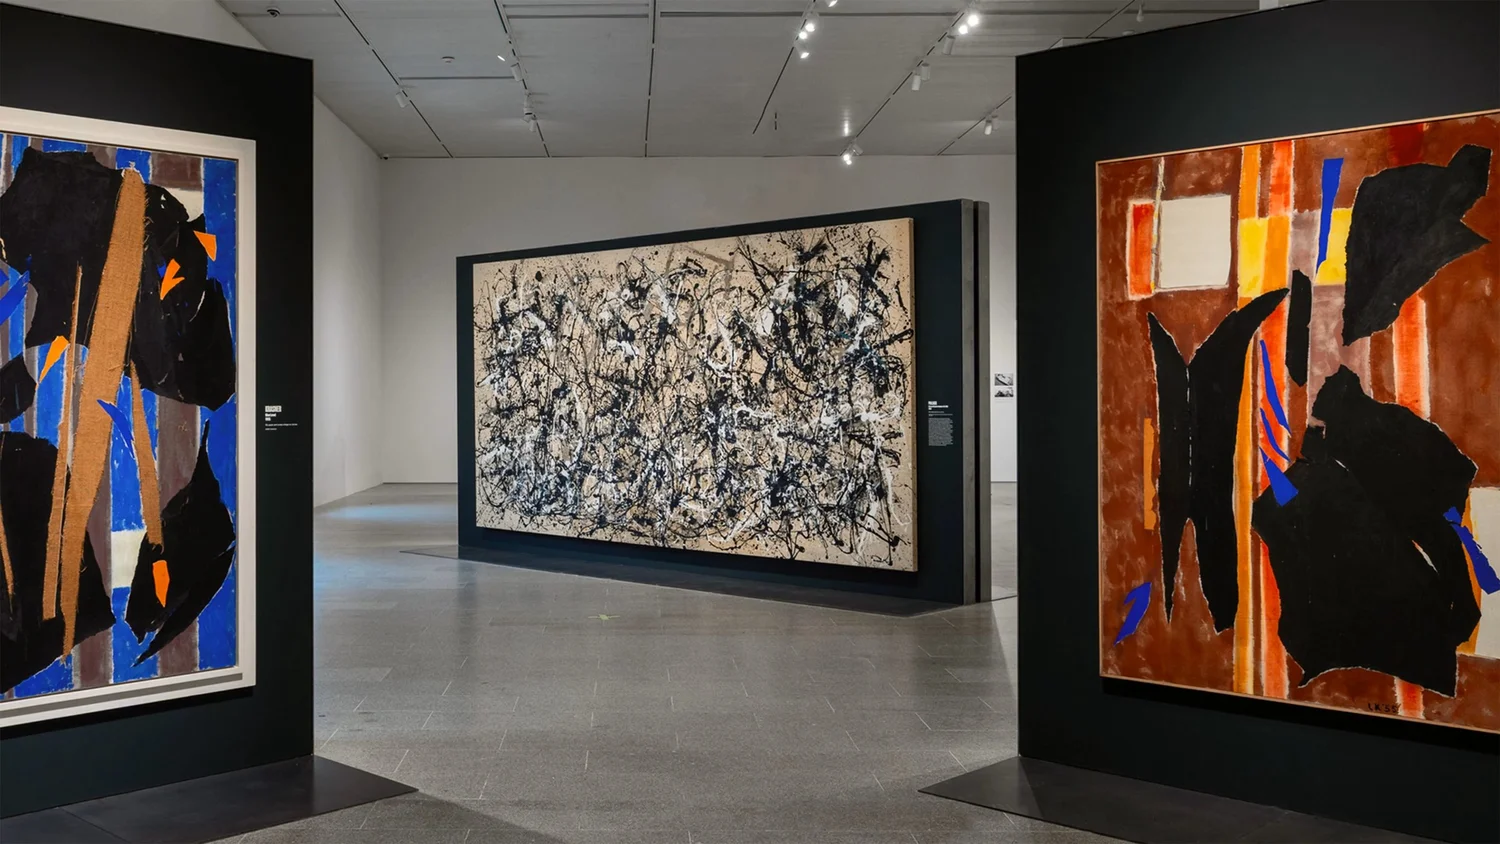
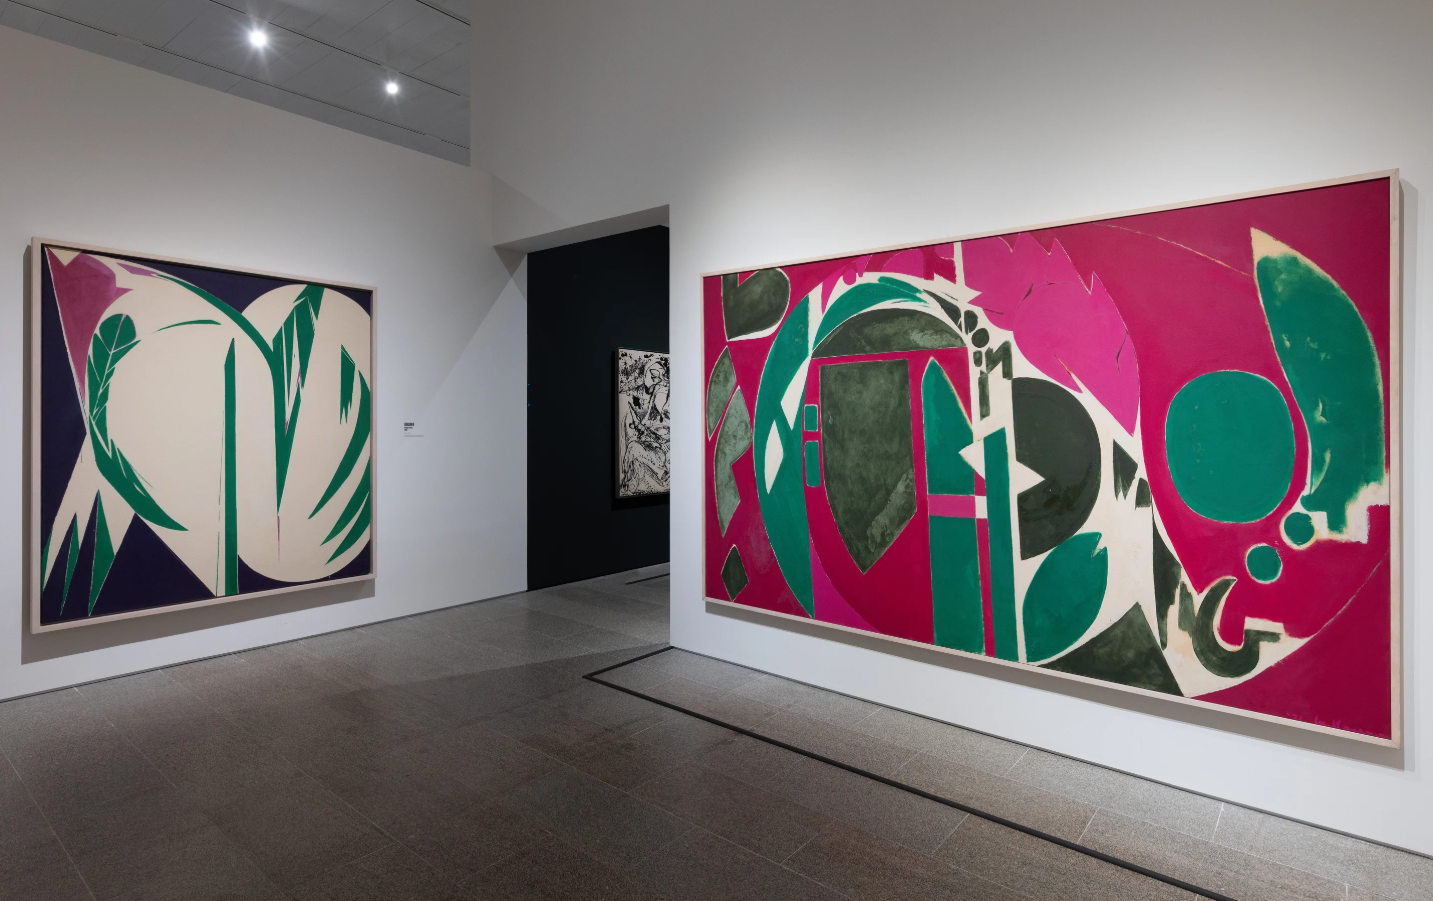
This fall season, New York is playing host to a suite of exceptional museum exhibitions. Among others, the Metropolitan Museum of Art’s superlative pairing of Lee Krasner and her husband Jackson Pollock has united a wealth of each artist’s work under one roof, a gathering rivaled only in rarity by the number of masterpieces on display at the Whitney Museum’s Roy Lichtenstein retrospective, curated under the direction of contemporary artist Alex Da Corte.
All three of these artists currently celebrated in the art world’s capital occupy positions at the top-end of the international art market. For Pollock and Lichtenstein, this has long been the case; decades of scholarship, museum exhibitions, and gallery shows have cemented their place within the art historical canon. Krasner, on the other hand, was only entered its upper echelons in the last decade or so, driven in part by a reassessment of her career beyond the shadow of her husband’s oeuvre – a repositioning that the Met’s show seeks to develop further.
For a market that does not rest on intrinsic value, institutional validation and acceptance into art history act as important signifiers of long-term monetary value. What, therefore, can a deep dive into museums and the market reveal about the relationship between these two poles of the art world? While Pollock’s signature ‘drip’ paintings are so rare that transactions already occur in the rarefied air of the so-called ‘masterpiece’ market, what effect might these two acclaimed museum exhibitions have on Krasner’s and Lichtenstein’s markets going forward?
Institutional validation and price movement
When museums hold major exhibitions of an artist, a group, or a movement, there is often a correlated rise in the corresponding market. This may occur either in anticipation of or response to the presentation, and may be equally applicable to a younger artist enjoying a mid-career retrospective or a historical figure at the center of a posthumous survey. The British painter Peter Doig, for example, saw the average sale price for his work climb in a three-year period from $0.3M (2006) to $1.9M (2009), on either side of his first career retrospective staged at Tate Britain, Musée d’Art Moderne de la Ville de Paris, and the Schirn Kunsthalle Frankfurt (February 2008 – January 2009). Similarly, a second run of museum exhibitions between 2013–15 contributed to another spike in prices: from $1.9M in 2013 to $5.3M in 2015, before rising to a peak of $8.1M in 2018.
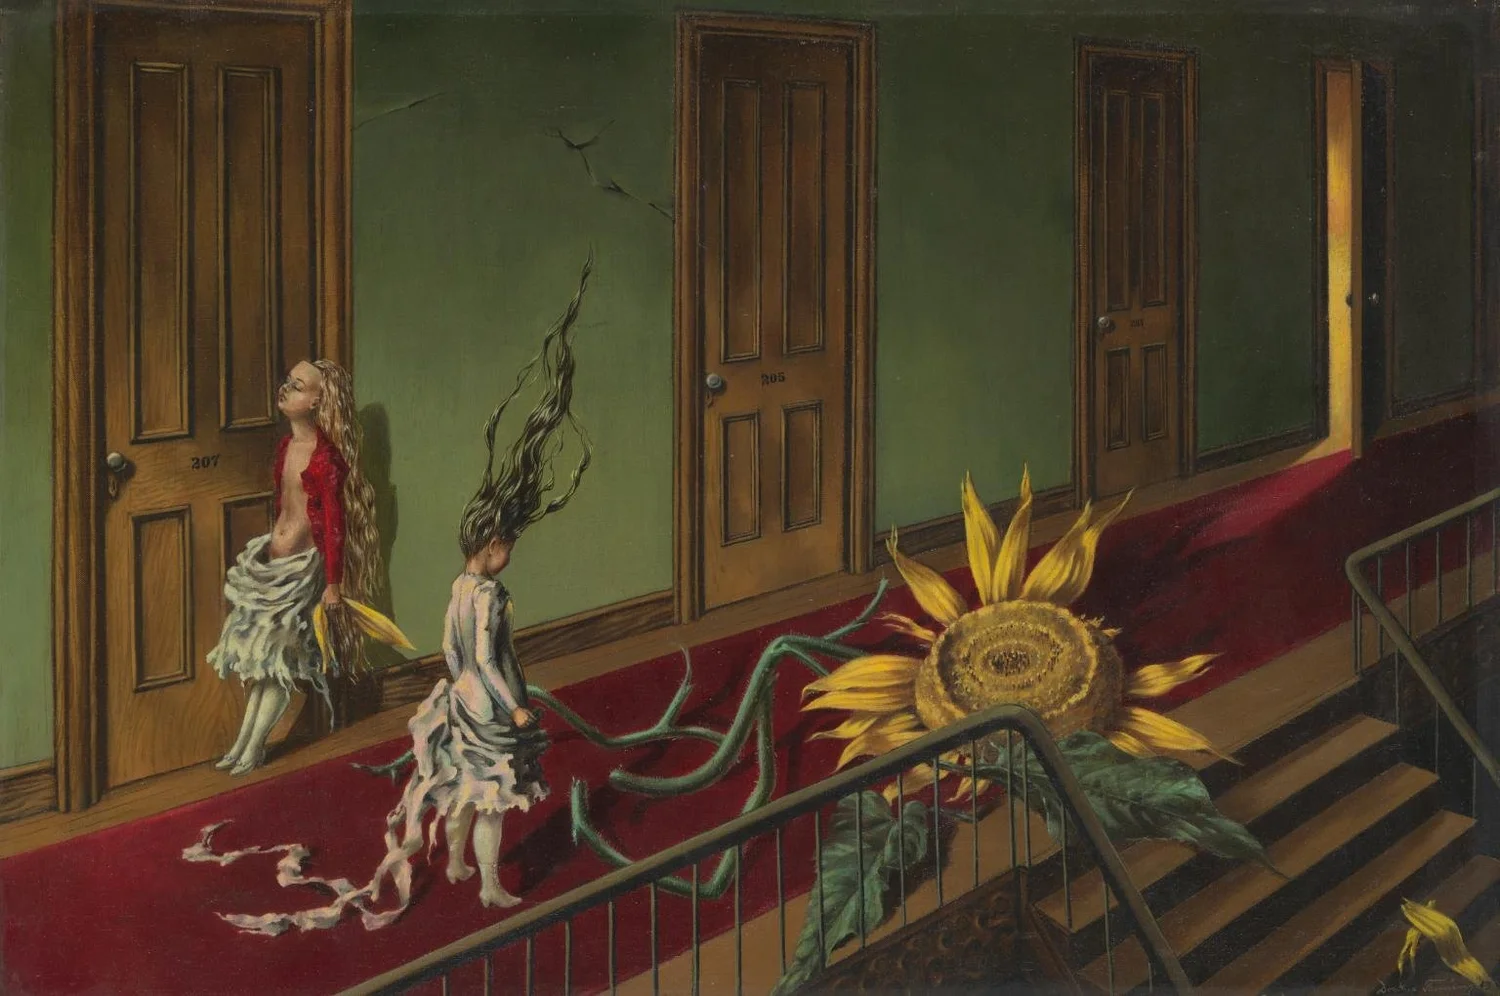
Whereas Doig received sustained critical and market attention relatively early in his career, the exposure afforded to female Surrealist artists long lagged behind that of their male counterparts. A refocusing of scholarship to address this imbalance has resulted in a number of recent major museum exhibitions devoted to the work of female Surrealists: solo retrospectives of Dorothea Tanning (2019) and Remedios Varo (2023), and group surveys at the Met (2021), Tate Modern (2022), and the Peggy Guggenheim Collection (2022), among others. The market has followed this renewed focus on the category, with average prices rising nearly four times from $52.7k in 2018 to $183.1k in 2020. The strong momentum has continued, with year-on-year increases to an average price of $612.9k thus far in 2026.
Figure 1. Doig and Female Surrealists: price follows major museum surveys
Peter Doig solo exhibitions at Tate Britain, Musée d’Art Moderne de la Ville de Paris, and Schirn Kunsthalle Frankfurt (February 2008 – January 2009); Scottish National Gallery and Musée des Beaux-Arts de Montréal (August 2013 – May 2014); Fondation Beyeler and the Louisiana Museum (November 2014 – August 2015). Dorothea Tanning at Tate Britain (February – June 2019); Surrealism Beyond Borders at The Metropolitan Museum of Art and Tate Modern (October 2021 – August 2022); Surrealism and Magic at the Peggy Guggenheim Collection (April – September 2022); Remedios Varo at the Art Institute of Chicago (July – November 2023). ‘Female Surrealists’ consists of aggregated auction results for Dorothea Tanning, Remedios Varo, Leonora Carrington, Leonor Fini, Meret Oppenheim and Dora Maar. Paintings $50k+ only.
Museum/market correlation often depends on pre-existing price levels
The link between institutional exposure and market development is often most pronounced at lower price levels, where there is a wide pool of collectors newly (re-)introduced to an artist able to compete for their work. In line with continuing revisions to the canon, many of the markets that have seen the most significant upticks have been those of female artists or artists of color, rather than those of white male artists who have historically had more prominence as the subject of critical attention. The growth of these markets – Alma Thomas, Alice Neel, Ruth Asawa, Howardena Pindell, among others – alongside museum surveys has also acted as a foil to the increasing scarcity of exceptional works by established modern masters. The repositioning of a new coterie of artists over the last decade – frequently at a more accessible, sub $1M price point – has brought a flow of new supply into the marketplace that has fed established and new collectors’ appetites alike.
| Artist | Sales | First $1M+ sale | $1M+ sales | Highest sale | 3-Yr Moving Avg. Δ |
|---|---|---|---|---|---|
| Alma Thomas | 35 | 2019 | 10 | $3.92M | +135.2% (2020–23) |
| Ruth Asawa | 71 | 2013 | 20 | $5.38M | +81.7% (2017–20) |
Table 1. Growth at the $1M level for lower-priced markets
Figure 2. $1M+ sales arrive after repositioning
Dark bars: sales of $1M or more; light bars: sales under $1M (left axis). Alma Thomas touring retrospective traveled to the Chrysler Museum of Art, Phillips Collection, Frist Art Museum, and Columbus Museum (July 2021 – September 2022). Ruth Asawa: Life’s Work was held at the Pulitzer Arts Foundation (September 2018 – February 2019). Alma Thomas Paintings: Ruth Asawa Sculpture $50k+.
The reverse also holds. Where an artist already trades at the highest level ($10M+) and is collected by established, tastemaking collectors, a museum exhibition is less effective at reaching a new pool of collectors who could take the work to the next level. Logically, the more expensive a market is, the smaller the collecting pool; likewise, the more established the name, the less scholarly or price discovery there is to be had. This ceiling effect can limit value growth, and when estimates are ambitious or private sale prices are pushed up too soon, the result can be unsold lots and less confidence at the very top.
Brice Marden illustrates this ceiling effect. Average prices rose after his major retrospective at MoMA and the San Francisco Museum of Modern Art (2006–07) but have since been uneven. Since 2020, five significant paintings with low estimates of at least $4M have been withdrawn or failed to sell, including Event (2004–07), offered in May 2024 with a $30–50M estimate; during this period, his work has been the subject of exhibitions at the Menil Drawing Institute, Kunstmuseum Basel, and MoMA. As an artist already placed with leading collectors through the primary market, Marden has a mature, fully priced market and a narrow collecting base, and the resulting volatility has become a recurring feature of his sales. With a high floor, uncertain ceiling, and slim capacity for discovery, market participants may be hoping for price consolidation, rather than significant upticks, an outcome that Gagosian’s current, museum-quality display of Marden’s work in New York could help bring about.
Institutional attention brings rare acquisition opportunities to market
Moments of institutional attention often bring to market more work, or higher-caliber work, than would otherwise appear. The art market is predominantly driven by supply-side dynamics; on the occasion of a major museum exhibition, auction house specialists and dealers have stronger case to convince sellers to consign works for sale. Seeking to capitalize on momentum and attention, they can pry important works from private collections that, when sold, reset an artist’s market at a higher level.
Arguably the most important work by the Surrealist painter Leonora Carrington came to market at a time when awareness and understanding of female Surrealism had reached new levels. On the back of numerous exhibitions devoted both to Carrington herself (2013–15, 2018, 2022–23) and the wider category, Les Distractions de Dagobert (1945) achieved $28.5M at Sotheby’s in May 2024. The result set a new benchmark for her own market, and elevated masterpieces by female Surrealists into similar price bands as their male counterparts.
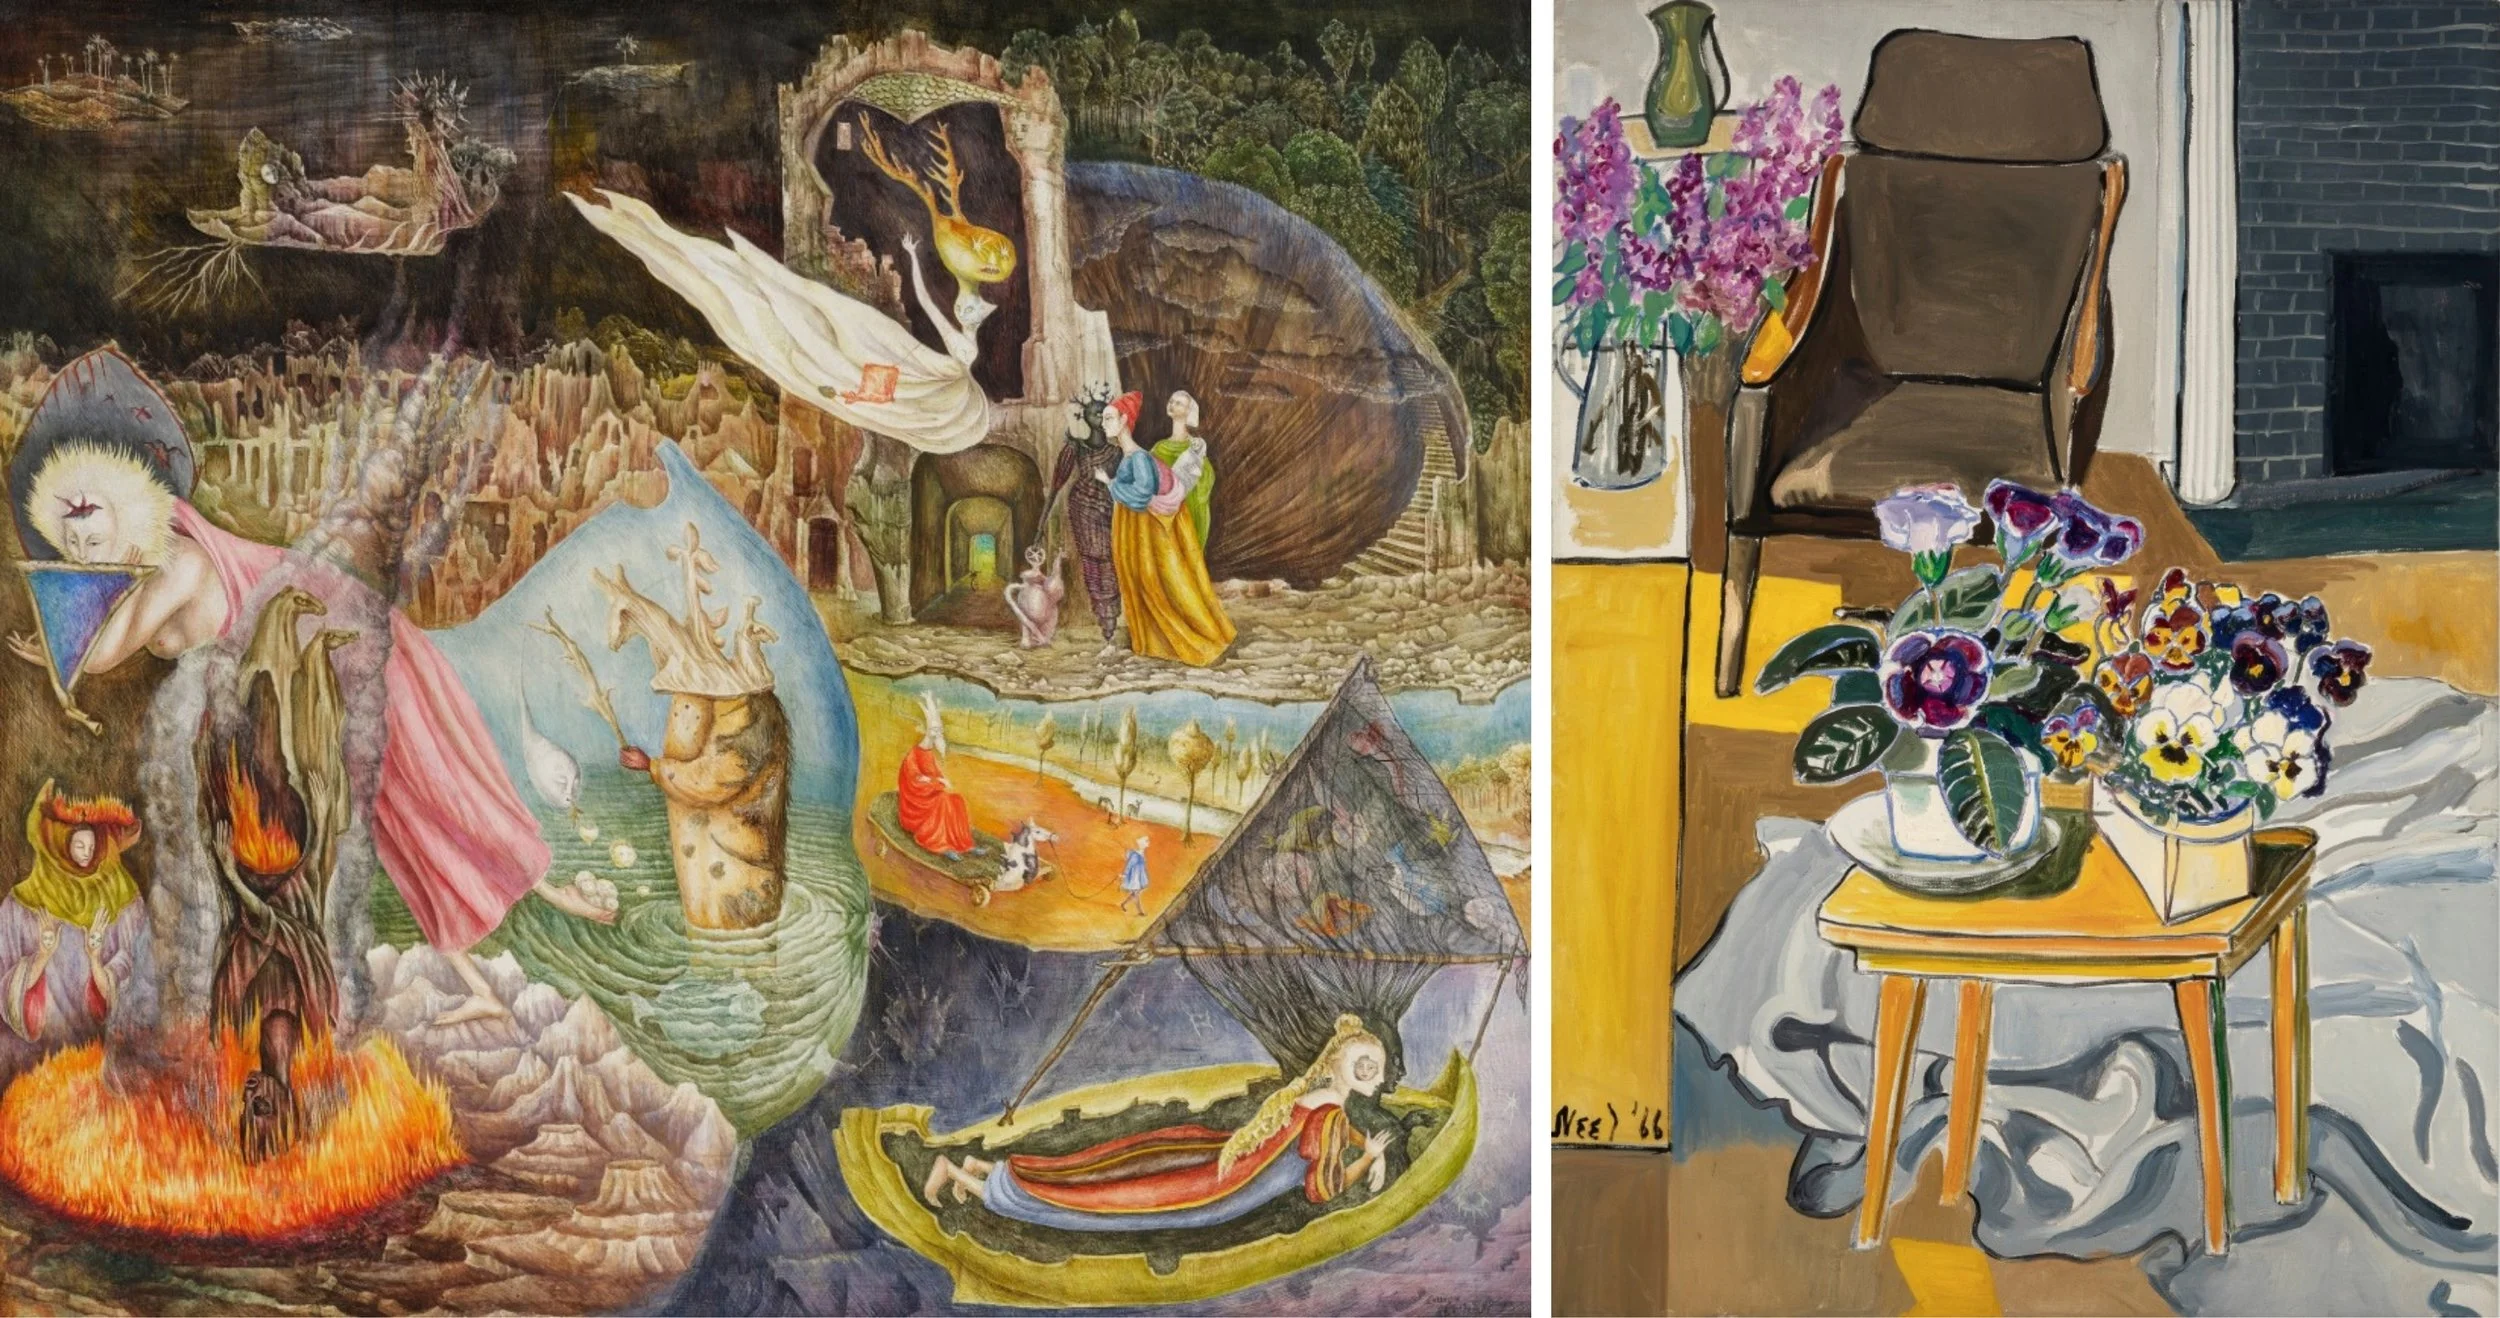
Right: Alice Neel, Dr. Finger’s Waiting Room, 1966. Oil on canvas, 127 x 91.4 cm. Private Collection. This work set a then-auction record in 2021.
Increased focus on an artist at an institutional level – together with anticipated collector demand – also often brings a greater volume of works to market. In 2021, the year of Alice Neel’s celebrated retrospective at the Met, 10 works came to market; four of these works achieved $1M+, one of which set an auction record at the time. Between 2021–23 – the years spanning Neel’s Met show and European touring retrospective – 17 works were sold at auction, compared to 12 across the previous five years.
Figure 3. Carrington and Neel: volume and top lots arrive with museum exhibitions
Dark bars: sales of $1M or more; light bars: sales under $1M (left axis). Leonora Carrington has been the subject of solo museum retrospectives at the Irish Museum of Modern Art (2013–14); Tate Liverpool (2015); Museo de Arte Moderno & MARCO (2018); ARKEN Museum of Modern Art & Fundacion MAPFRE (2022–23); Palazzo Reale & Musée du Luxembourg (2025–26). A retrospective of Alice Neel’s work was held at the Metropolitan Museum of Art and the Guggenheim Museum, Bilbao (March 2021 – February 2022). A European retrospective tour traveled between the Centre Pompidou, Barbican Center, and the Munch Museum (October 2022 – November 2023). Paintings $50k+ only.
Looking Ahead: Lichtenstein & Krasner
For artists who are extremely established within art history, one more exhibition, such as the Roy Lichtenstein exhibition at the Whitney, is unlikely to shift the market. As with the ceiling effect discussed above, Lichtenstein’s major works in private hands already trade within a rarefied circle of collectors (take, for example, mega-collector Steve Cohen’s purchase of Masterpiece (1962) for c.$165M in 2017). Macroeconomic and broader market conditions contribute to present price levels more than further institutional exposure; in the current uncertain global environment with higher interest rates, many major Lichtenstein paintings are unlikely to trade at a premium to what they commanded a decade ago.
This being said, there has been increased market activity for artworks Lichtenstein executed in mediums generally associated with more accessible price points. Since 2020, there has been an uptick in prices for works on paper and sculpture, in contrast to the relative flatlining of results for his paintings. This is undoubtedly driven by the Lichtenstein Estate’s recent collaboration with Sotheby’s (May 2024–present), which has brought a steady supply of rare preparatory studies and editioned sculptures to market. But it also points to collectors turning to more accessible and readily available segments of the artist’s market in a continued effort to add instantly recognizable, definitively blue-chip works to their collections.
Figure 4. Lichtenstein: works on paper and sculpture rise while paintings flatten
3-year moving average of the yearly average auction price for Roy Lichtenstein’s paintings, works on paper and sculpture (log scale). Averages draw on sales from 2018 onward; 2026 is year to date (to October 2026). Prints and editions excluded. Source: Arthur Analytics.
Much as the attention generated by Lichtenstein’s exhibition at the Whitney may cement higher trading for a broader range of mediums, a similar re-evaluation can be seen occurring for different periods in Lee Krasner’s work. The correlation between institutional focus and market reassessment is exemplified by her market: the current record price for Krasner’s work was set for The Eye Is the First Circle (1960), which realized $11.7M in May 2019, just as her landmark European touring retrospective Living Colour (Barbican, Frankfurt, Bern, Bilbao; 2019–21) was opening. The average rose from $0.9M (2018) to $3.5M (2019) and $5.6M (2021) on three top lots ($11.7M and $7.4M in 2019; $9.0M in 2020), then eased to $2.5M by 2026, roughly 2.6 times the 2018 level.
Attention has long focused on works she produced alongside Pollock before his death in 1956. Recently, however, her later work has come to the fore, partly due to the comparative scarcity of earlier examples. A 2017 exhibition at Kasmin Gallery centered on the ‘Umber’ paintings of the early 1960s; the Met exhibition closes with an extended display of her late work; and Gagosian’s current Krasner exhibition also focuses exclusively on her paintings of the 1960s. Critical and market attention has again evolved together: the top-three auction results for works executed in the 1970s have been set since May 2023, while the highest result for a 1980s work was realized in November 2025.
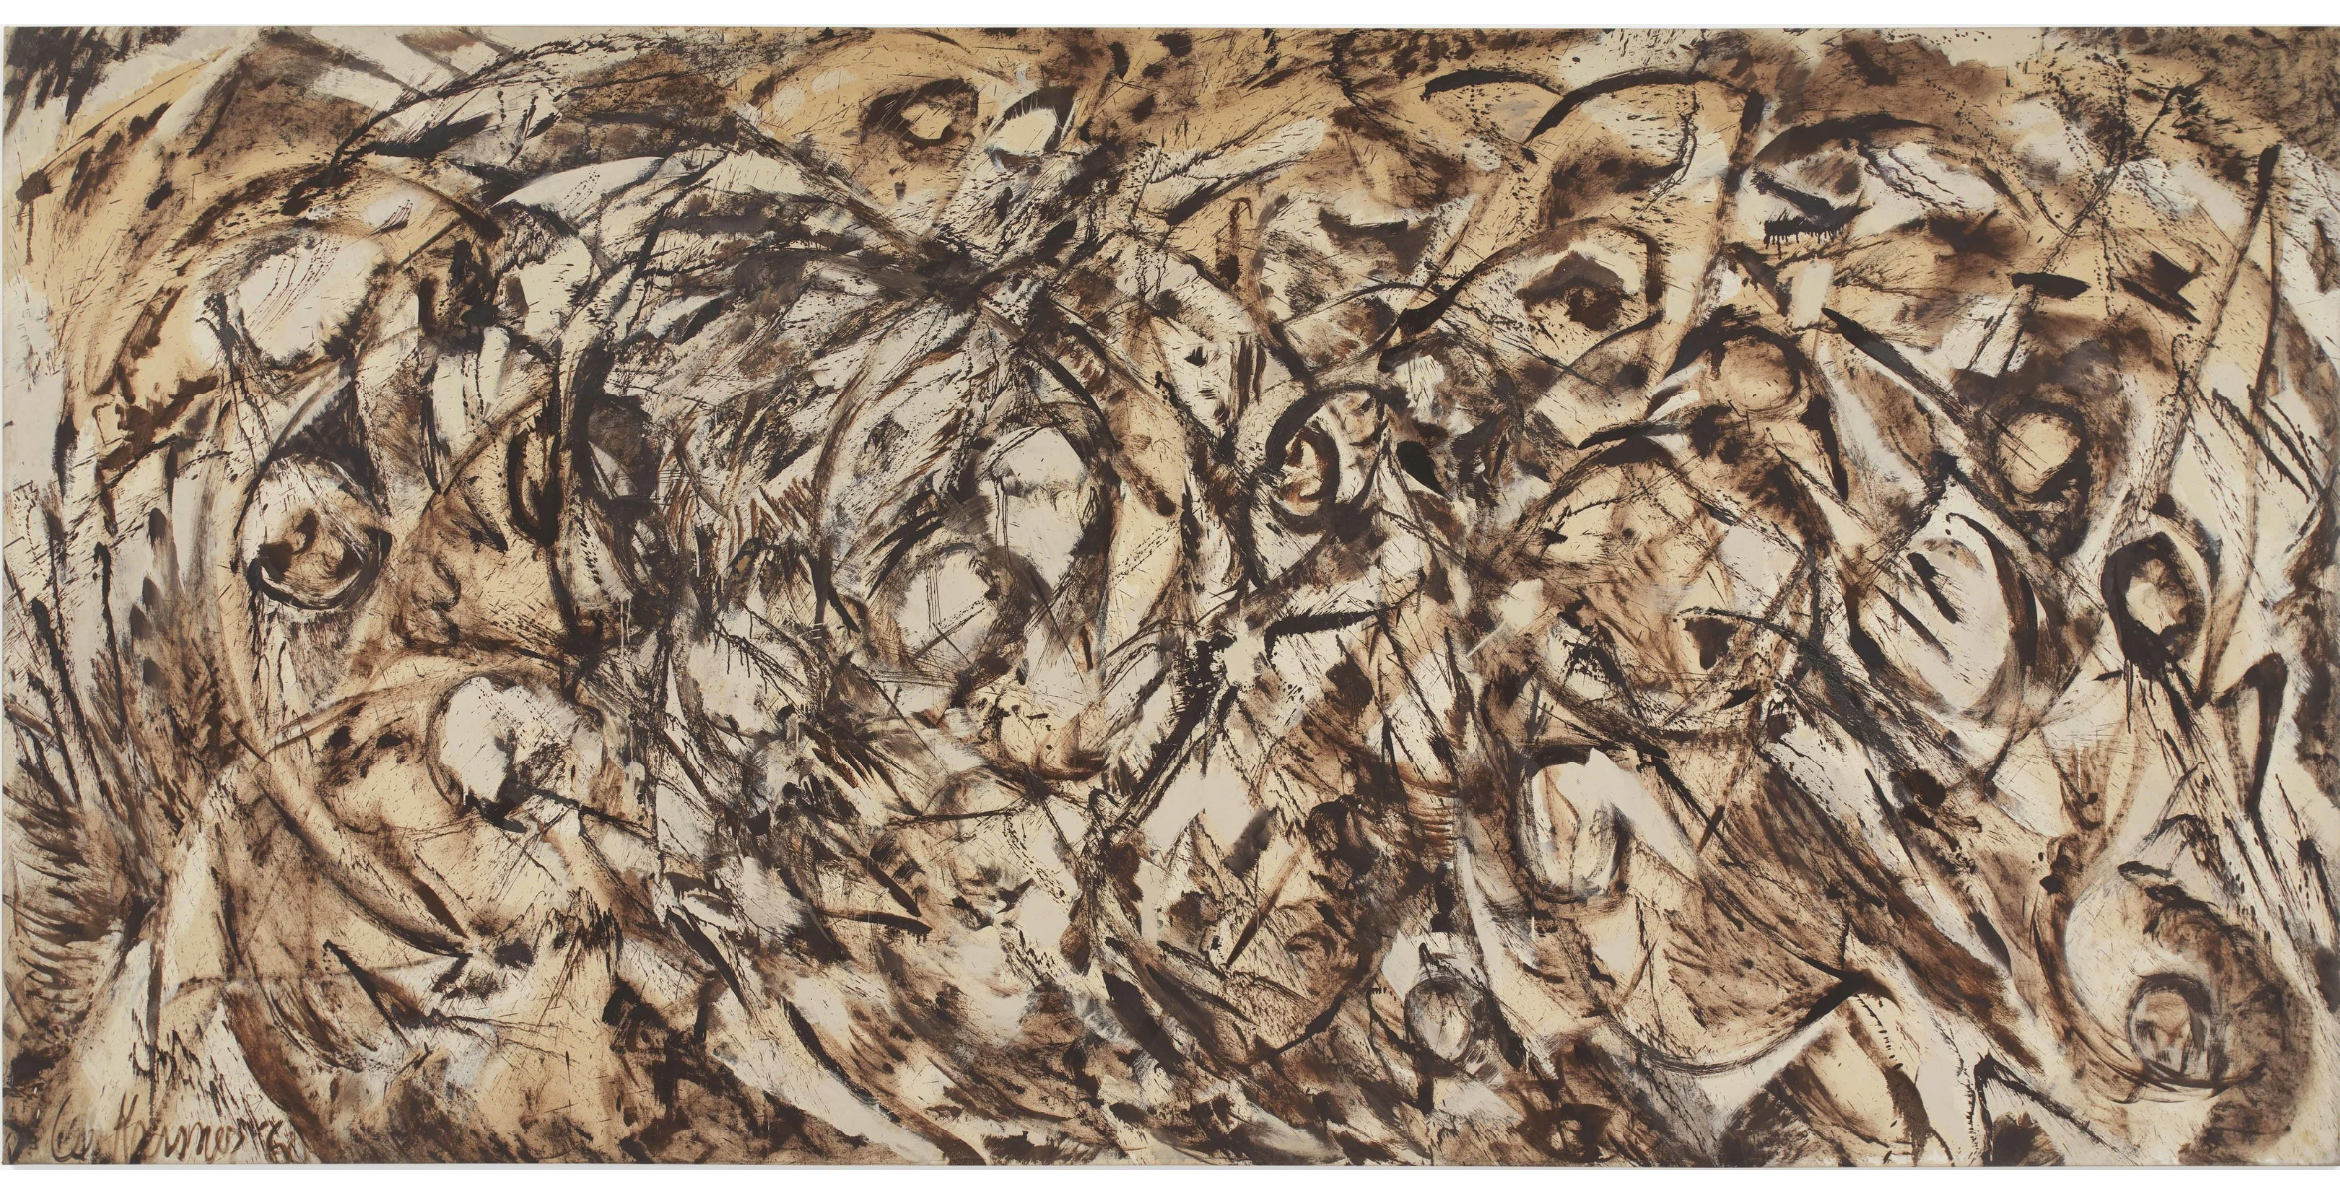
A showstopper exhibition may encourage a headline sale for these two artists; indeed, a large 1990 Lichtenstein canvas is slated to lead Sotheby’s upcoming Contemporary Evening Sale in New York next month. Yet the sharpest market responses to museum attention described above took place where the entry point was low enough for a broad pool of newly introduced collectors to compete. This is not the case for Lichtenstein, whose major paintings are already out of reach to all but the most deep-pocketed collectors: many buyers are turning to works on paper and sculpture. The critical and market reassessment of Krasner’s role within the landscape of post-war abstraction is far from finished. However, the scarcity of her work and its steady acquisition by institutions or leading collectors makes it unlikely that a consistent supply of masterpieces will emerge to drive her prices to heights far beyond their current level. With demand still strong, it is unsurprising that a market is now developing for her later work. In the case of both Lichtenstein and Krasner, the lasting effect of these major New York exhibitions may be best understood as catalyzing greater market depth across different mediums, periods, and subjects, diversifying competition across a broader cross-section of their oeuvres. Growth of this kind is slower, but arguably more durable.
On view at AIG
17 September – 11 December 2026
Suite A, 1/F TS Tower, Heung Yip Road, Wong Chuk Hang
Art Intelligence Global is pleased to present “Significant Form”, the most significant display of Modern and Contemporary South Asian Art staged in Hong Kong to date. Produced in collaboration with three of Mumbai’s leading galleries – Chemould Prescott Road, Jhaveri Contemporary, and TARQ – this group exhibition brings together eleven artists, spanning from the post-Independence period through to the present day. Between established modern masters and leading contemporary artists working today, the exhibition explores their varied engagement with the complex histories, places, memories, and identities of the region.
Exhibition Recommendations

Copyright Art Intelligence Global, 2026.
All rights reserved.
Reach us at:
32 E 57th Street Floor 12
New York, NY 10022 USA
Suite A, 1/F, TS Tower
No. 43 Heung Yip Road, Hong Kong
info@artintelligenceglobal.com